CONFIDENTIAL INFORMATION · PUBLIC MONEY · AUTHORIZATION
Who had access. What was verified.
A documented confidential-information release. Reported exposure through a public portal. A vendor-impersonation theft. Questions about signatures and account authority. These records raise a shared oversight question: how does the City verify access, authorization and disclosure—and document that problems have been corrected?
Records and correspondence through September 25, 2026
01 / DISCLOSURE & RESPONSE
Documented release and reported public exposure
An acknowledged release · May 2026
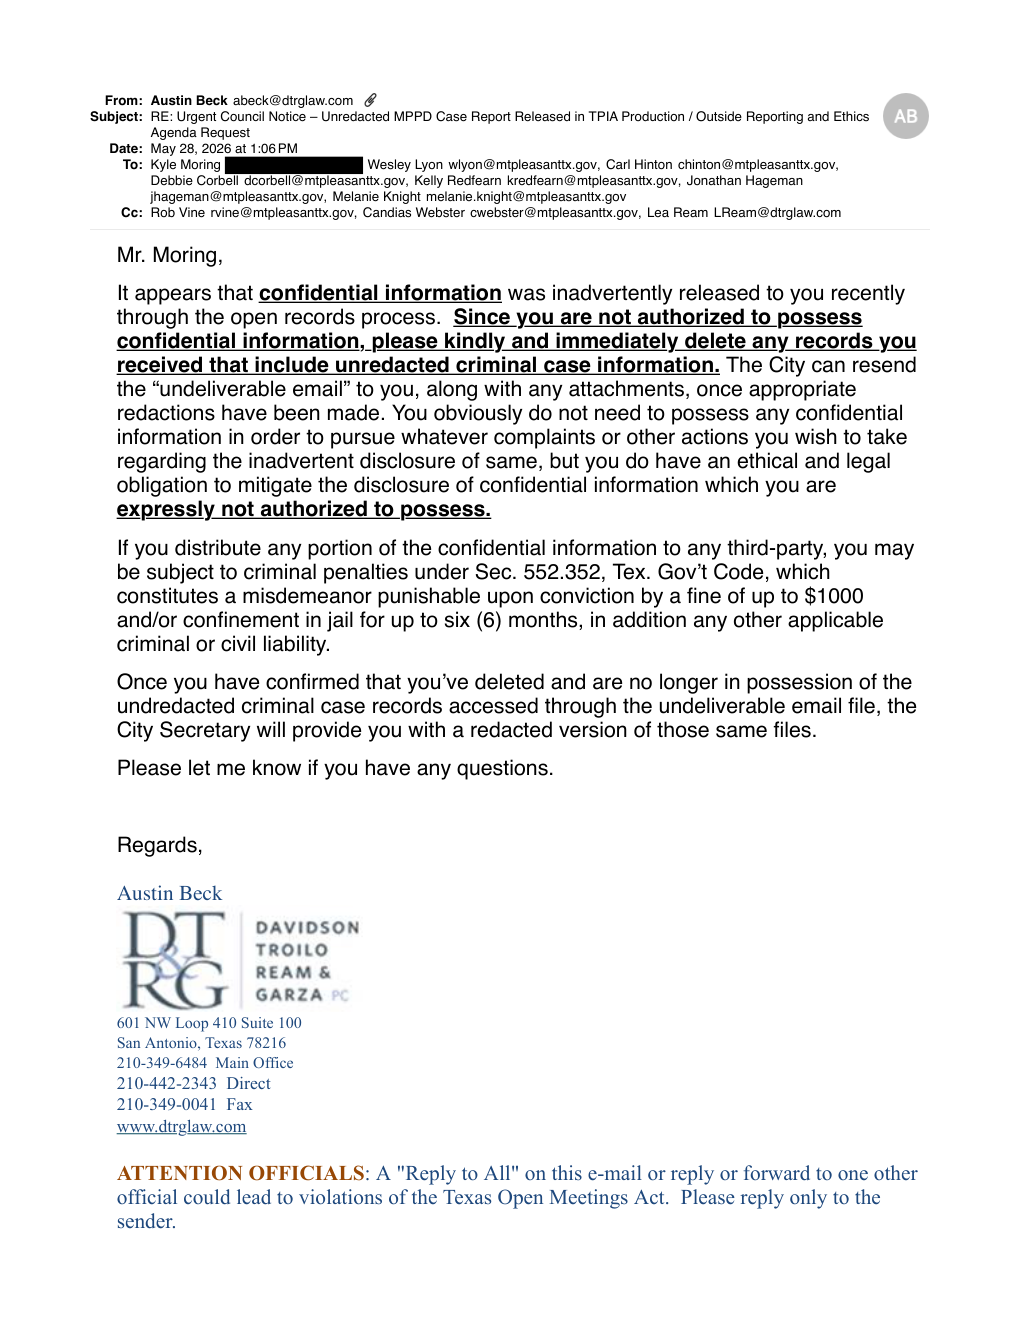
After Kyle reported an unredacted police-record attachment, Austin Beck’s May 28 response stated that confidential information appeared to have been inadvertently released through the open-records process. He requested deletion and offered a redacted replacement. That acknowledgment is evidence of a disclosure problem; it does not establish every category of information alleged or the full scope of exposure.
Portal and customer-data concerns · April–May 2026
Kyle’s April 28 and 29 Council notices reported apparent SSN-format values and sensitive patient-related information in public financial exports. Vine’s April 28 response said the City would investigate and work with its partners. Separate May notices raised Schneider customer and payment information. The notices establish what Kyle reported; they are not a completed technical investigation.
Webster’s May 27 signed certification identifies Kyle’s notice but says the City located no records responsive to Items 1–25 other than Kyle’s own communication. That is difficult to reconcile with Vine’s City-generated acknowledgment and stated plan to investigate with the City’s partners. The focused question is what custodians, accounts and systems were searched and why Vine’s response was not produced or treated as responsive.
A replacement PDF addresses one delivery. An incident assessment, access history, preservation record and documented corrective action address who could access the information and whether the exposure was contained. Kyle’s August 19 Council submission asks for that broader accounting. The underlying sensitive records are not reproduced here.
The financial statements and the control findings answer different questions
FY2023: responsibility and audit scope
The FY2023 ACFR places responsibility for internal controls with management. The auditor explains that understanding those controls for the financial-statement audit is not an opinion on their effectiveness. This language does not itself establish that the later vendor-payment weakness was identified in FY2023.
The separate FY2024 single-audit report identifies closing-process deficiencies (2024-001) and inadequate verification of vendor-payment changes (2024-002) as material weaknesses. It records a $557,340 loss from vendor impersonation. Management’s corrective-action plan says new vendor-payment-change processes had begun. That plan is a commitment, not proof of completed remediation.
The FY2024 ACFR separately reports $1,100,340 stolen, $543,000 recovered and a $557,340 net loss at the time of the report. Read the theft disclosure · PDF page 81 ↗
Council had also been asked to review controls
Kyle’s February 6 submission requested an independent internal-controls review concerning police and records processes. His May 12 escalation raised access to audit and Council records, and his June 6 notice requested independent review of the City’s TPIA production controls after the acknowledged disclosure. These were requests for Council oversight; they are not external-auditor findings and do not establish that Council adopted the requested action.
A June ruling. A September production. Completeness still disputed.
OAG orders release
OR2026-027532 finds that the City failed to submit the requested information or a representative sample for review. It orders release and directs a court challenge if the City believes information cannot lawfully be released.
The City produces records; Kyle acknowledges receipt
Beck transmits records, describing them as all responsive information and identifying access-device-number redactions. Kyle confirms receipt of five PDFs totaling 517 pages and acknowledges finding embedded attachments. He requests clarification of completeness and reading order. The reply signed by paralegal Marla Dial, sent from Ream’s address, confirms the page total and defers remaining questions to Beck.
The September production does not by itself resolve whether the records were timely or complete, or the pending §552.3215 complaint. As of September 25, Kyle reports that no determination has been received. Read the complaint-status account →
04 / A LATER AUTHORIZATION CONCERN
Hunter Bonner’s August 18 public comment
During public comment, Bonner said Assistant City Manager Candias Webster contacted him after two City internet-fiber circuits had been renewed with his name in the electronic-signature field. He said he immediately denied signing the contracts, that the associated email address was not his, and that Webster then asked whether he knew of anyone using his email address and name. He also said he was directed to file a public-information request before seeing the referenced material and that vendor-account offboarding remained incomplete years after he left City IT work.
Bonner’s remarks document what he publicly reported and how he interpreted Webster’s response. They do not establish who created or used the signatures, whether Webster shared that interpretation, or that this incident arose from the same control weakness as the FY2024 vendor-payment theft.
The signed copy lists Director of Finance and Account Manager as authorized titles, but identifies only “Laurie Mays respectively.” An unsigned version names “Laurie Mays and Candias Webster, respectively.” The difference is visible in the records; these copies alone do not establish who edited the text or which exact version Council adopted.
The executed LOGIC form raises a separate question
The executed form shows Webster signing in Part II as a representative being added, signing again in Part III as a currently authorized representative approving the additions and deletion, and completing the attestation. Thatcher also appears as a currently authorized representative. The form does not explain how Webster was simultaneously being added and acting as an existing approver.
Resolution 2022-5 names the City Secretary and Webster and says its designation continues until rescinded or employment ends. That may provide a continuing-authority explanation, but the available records do not show which authority LOGIC relied upon.
The response and the produced records do not align cleanly
The City marked request Items 4 and 5—records bearing Webster’s signature or identifying her in specified account roles, and Guaranty records naming her—“No information related to this request.” Records attached under Item 6 nevertheless bear her signature and identify her as an authorized representative or account contact. Resolution 2025-11 also expressly names her as a Guaranty Bank signatory but was not included in the production.
The January 25, 2023 Guaranty transmittal was supplied as a flattened PDF rather than the requested native .eml or .msg message with headers and its original attachment. That limits verification of the precise file transmitted, its metadata and its delivery history.
The practical question is what each financial institution received, which authority it relied on, and what record verifies the approval. Institution-held copies and transmission records would help reconcile the versions.
06 / LOOK AT THE DOCUMENTS
Signature appearance is a reason to ask, not an identification of the signer
Kyle questions the appearance of the signature reading “Ed Thatcher” in the LOGIC approval block when compared with signatures attributed to Thatcher in published Mount Pleasant and Heath records. The copies permit a visual comparison; they do not establish who physically wrote any signature. Normal variation, copying and different signing methods can affect appearance. Originals, institutional records and qualified document examination would be needed to resolve authorship.
Eleven City travel-request forms obtained from Carl Hinton’s public Facebook profile cover August 2022 through June 2023. The August 2022 form bears an approval signature reading “Ed Thatcher” on the Department Director line; the other ten appear to bear Webster’s signature on that line. The forms raise a separate question about who approved Council mileage claims and under what authority.
KLTV’s February 2025 reporting describes indictments arising from a Texas Rangers investigation of Council mileage reimbursements involving current and former City officials. Those charges are allegations, not findings of guilt. The selected forms have not been established as the transactions underlying the charges, and their aggregate does not match the amount reported for the Chappell allegations.
Webster held the titles Assistant City Manager and City Secretary, and separate records show financial-account authorization roles. Those facts support asking what authority and control responsibilities applied to each account. They do not establish that she supervised the Finance Department or was responsible for the vendor-payment theft.
THE CONNECTION TO OVERSIGHT
What changed—and where is it documented?
The common question is whether the City can demonstrate who was authorized, how sensitive information was protected, and how corrective action was verified. The records establish different things: an audit finding, a disclosure acknowledgment, a public allegation, a disputed production or a visibly different document version. Kyle reports no Council response or decision addressing his August 19 oversight submission as of September 25. Compare each record with the response and draw your own conclusions.
The County ledger printed July 1, 2026 includes transactions from earlier fiscal years. This is a separate fund from the District Attorney’s seized- and forfeiture-fund records. The connection identifies where the ledger belongs; it is not a new financial finding or a review of all 43 pages. Read the ledger source entry ↗ · Titus County context ↗
Confidential information & financial controls | Mount Complacent